What Happens If Your Key Assumption Fails?
A personal reflection from Poland on assumptions, resilience and making better business decisions.
I had the opportunity to take part in Exercise POLISH TIGER 2026, a Management Accountancy Services (Army) conceptual study in Poland. It was very different from the usual kind of professional development. We travelled through Gdańsk and Warsaw, using historical events to explore questions around resilience, resources, dependency, opportunity cost and decision-making.
The point was not simply to learn the history. We were encouraged to test assumptions, challenge weak reasoning and think about how lessons from the past could improve decisions today. The study was designed around judgement, evidence and professional challenge rather than simply finding the “right answer”.
One question stayed with me more than any other:
What happens if your key assumption fails?
The question I had to answer
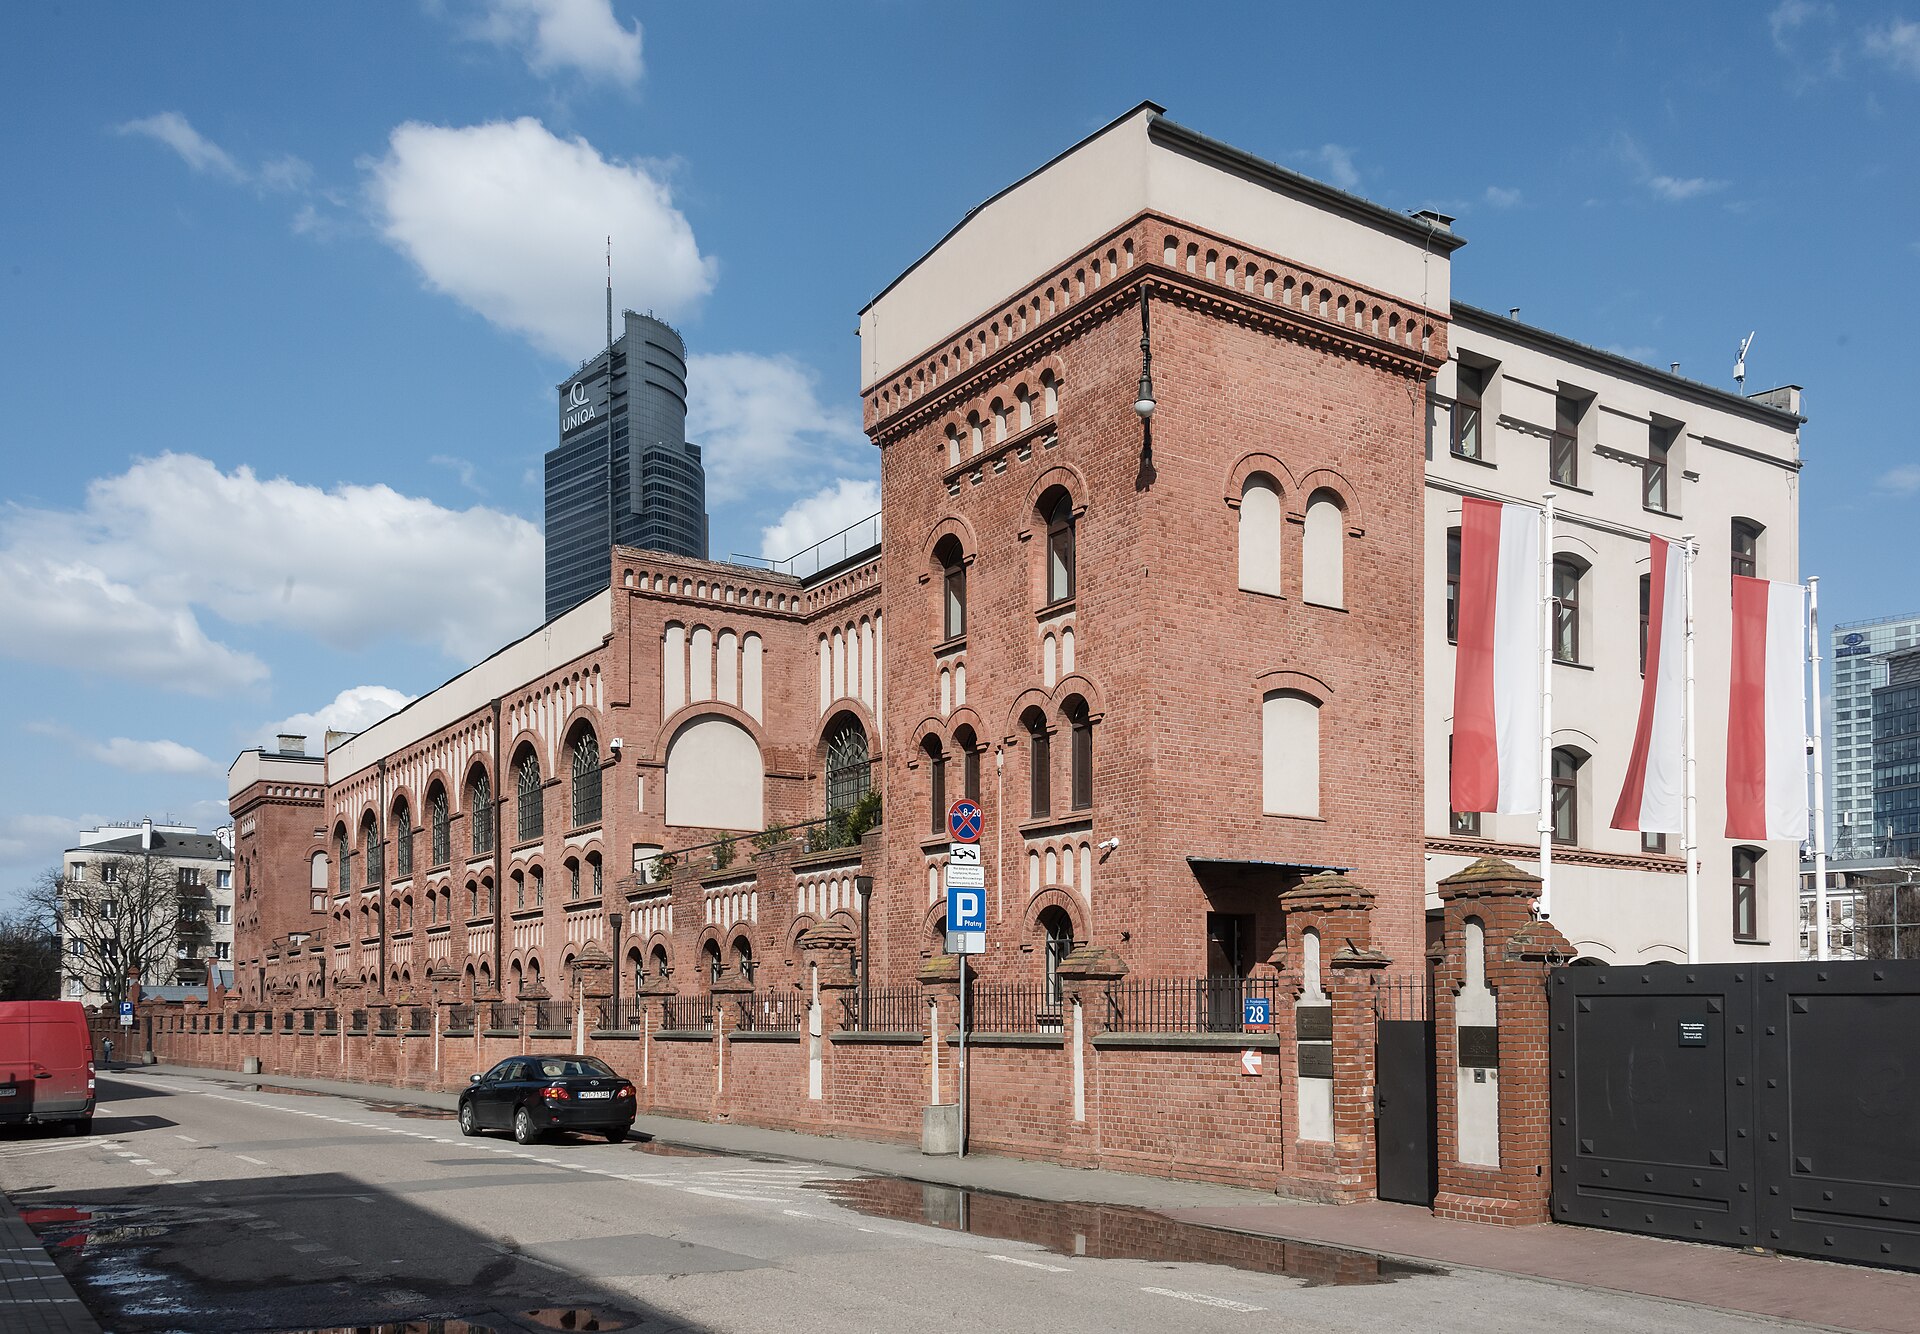
I was part of Syndicate 3, and my presentation took place at the Warsaw Uprising Museum. Our question was: Which assumption should a finance adviser have challenged first, what evidence was available, and what recommendation should have followed?
The Warsaw Uprising began on 1 August 1944. The Polish Home Army launched a major resistance operation, but the plan depended heavily on outside support. The resource position was already difficult: ammunition was expected to last only seven to ten days, air resupply was inadequate, Soviet forces had halted east of the Vistula, and the uprising eventually lasted 63 days before ending in surrender.
Standing in the museum and thinking through that question made something very simple click for me. The issue was not a lack of courage. There was plenty of courage. The issue was that an important plan depended on assumptions about what other people would do and when they would do it.
That is where the lesson started to feel very relevant to business.
Assumptions are not facts
Every business plan contains assumptions. You might assume your biggest customer will stay, your supplier will keep delivering, sales will grow, funding will still be available when you need it, or a key member of staff will remain. There is nothing wrong with making assumptions because none of us knows exactly what will happen next.
The problem starts when we stop treating an assumption as an assumption and start treating it as a fact. That is why I came away with three simple questions: What must be true for this plan to work? What evidence do I have that it will remain true? What happens if I am wrong?
Assumptions are everywhere
Every business plan contains assumptions, whether they are written down or not. You might assume your biggest customer will stay, your main supplier will keep delivering, sales will continue to grow, funding will be available when needed, or a key member of staff will remain.
There is nothing wrong with making assumptions. We all have to make them because none of us knows exactly what will happen next. A forecast, by definition, is based on what we think is likely to happen.
The problem starts when we stop treating an assumption as an assumption and start treating it as a fact.
That was probably the biggest lesson I took from the study. Before committing to a plan, ask three simple questions: What must be true for this plan to work? What evidence do I have that it will remain true? What happens if I am wrong?
Those questions sound simple, but they can completely change the quality of a decision.
Think about your biggest customer
Imagine a profitable small business where one customer provides most of the income. The accounts may look healthy, cash may be strong and the business may be growing, but there is one important assumption underneath all of that: that customer will stay.
The useful question is therefore not just whether the business is profitable today. It is also what happens if that customer leaves. Could the business still cover its costs? How long would the cash reserve last? How quickly could the lost income be replaced? Could anything be done now to reduce that dependency?
None of those questions mean the business is in trouble. In fact, the business may be doing very well.
The point is simply that a good set of numbers can still hide a weak dependency.
That is why understanding the story behind the numbers matters just as much as understanding the numbers themselves.
The same applies to suppliers
Now think about a business that relies heavily on one supplier. Perhaps that supplier is cheaper, reliable or has worked with the business for years. On paper, continuing with them might look like the obvious choice.
But what happens if that supplier suddenly cannot deliver?
Could someone else step in? Would prices rise sharply? Would the business have to stop trading temporarily? Would customers go elsewhere while the problem was being fixed?
The original decision to use that supplier may still have been completely reasonable. The real issue is whether the business has another option.
That is where the idea of resilience becomes practical. Resilience is not simply about preparing for disaster. It is about making sure one failed assumption does not remove all your choices.
A plan can be affordable and still be fragile
Another lesson from the study was that affordability and resilience are not the same thing.
A plan may fit within a budget and still be vulnerable. A business might be able to afford a new system, a new employee or a new contract, but that does not automatically mean the wider plan is strong.
You might buy a system that only one person knows how to use. You might take on a contract that makes one customer responsible for most of your turnover. You might choose the cheapest supplier even though there is no alternative if they fail.
In each case, the immediate financial decision may look perfectly sensible.
The weakness only becomes visible when you ask: what does this decision make us dependent on?
That is a question I think good financial advice should ask much more often.
Good advice should protect your choices
One phrase that stayed with me during the study was freedom of action.
In simple terms, I think that means having choices.
If something goes wrong and you have cash reserves, another supplier, several customers and people who can cover important roles, you still have options. If everything depends on one customer, one supplier, one employee or one source of funding, those options can disappear very quickly.
This is why I see good financial advice as more than reporting what has already happened. Of course, bookkeeping, accounts, tax and compliance all matter. But the numbers should also help a business owner look forward.
What are we relying on?
Where are the weak points?
Which assumptions matter most?
What can we do now, while we still have choices?
That is where financial information becomes useful for decision-making rather than simply record-keeping.
The question I brought home from Poland
The study in Poland covered far more than one topic, but this was the lesson that stayed with me most.
A plan can have a clear purpose, committed people and enough money behind it, yet still be fragile if one key assumption is weak.
The best time to challenge that assumption is not after things have gone wrong. It is before the decision is made, while there are still alternatives available.
For a business owner, that might mean building a cash reserve, finding a second supplier, reducing reliance on one customer, cross-training staff or simply testing a different scenario before committing to a plan.
None of that is about being negative. It is about being prepared.
The question I brought home from Poland is simple:
What must be true for your plan to work — and what will you do if it is not?
That is a question worth asking in almost any business.